IDGT Intentionally Defective Grantor Trust Diagram: 2026 Guide
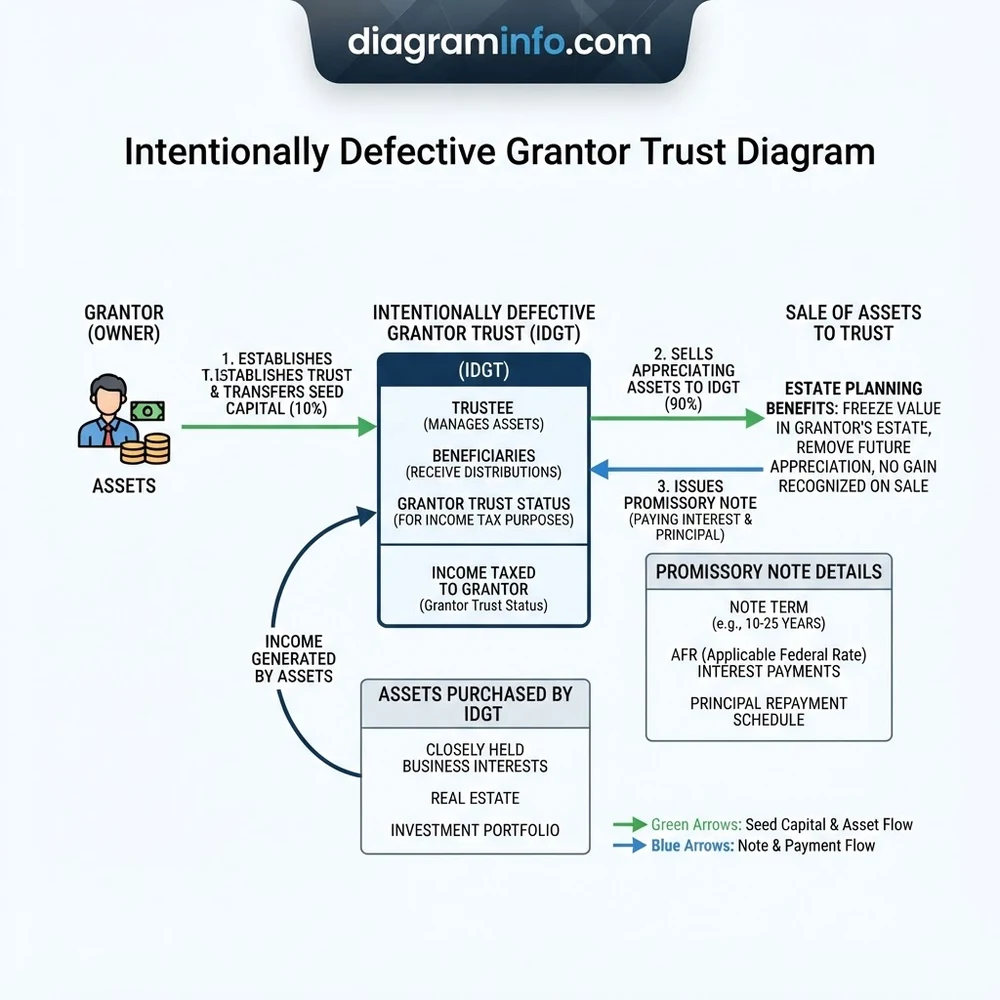
An intentionally defective grantor trust diagram illustrates the structural layout connecting the grantor, irrevocable trust, and beneficiaries. It details the initial 10% seed capital gift, the installment sale of appreciating assets via an AFR-based promissory note, and how grantor income tax liability allows tax-free asset growth outside the gross estate.
📌 Key Takeaways
- Requires an initial seed capital gift of at least 10% of total sale value to maintain legal entity integrity.
- Promissory note must use exact IRS Applicable Federal Rates (AFR) to prevent recharacterization as a gift.
- Grantor pays all annual income taxes on trust earnings, effectively making a tax-free gift to beneficiaries.
- IRC Sections 671-679 control grantor trust status while IRC Section 2036 excludes assets from the estate.
- Engage estate planning attorneys and CPAs to adjust configurations if IRS tax laws or valuations shift.
An intentionally defective grantor trust diagram illustrates the precise structural architecture used to decouple estate tax ownership from income tax liability under federal tax code provisions. By engineering an irrevocable trust layout that functions as a completed transfer for estate tax purposes (IRC Chapter 11) while remaining an incomplete transfer for income tax purposes (IRC §§671–679), wealth managers create an optimal environment for tax-free asset growth. This technical schematic outlines the individual components, structural connections, interest rate calculations, and asset flow protocols required to build, maintain, and troubleshoot an Intentionally Defective Grantor Trust (IDGT) system.


Structural Component Breakdown of an Intentionally Defective Grantor Trust Diagram


To analyze an intentionally defective grantor trust diagram effectively, each discrete operational component must be evaluated based on its statutory function, legal boundary, and financial interaction. The blueprint functions through five primary structural elements that establish a closed-loop economic system.
The Grantor (Settlor) acts as the primary power source in the system layout. The Grantor transfers seed capital and subsequently sells high-yield assets to the trust core. Under IRC §671, the Grantor retains intentional tax defects that force all income tax liabilities back to the Grantor’s personal tax return (Form 1040), effectively providing a tax-free compounding effect within the trust structure.
The Trustee functions as the operational controller. Responsible for managing trust assets, making distributions, and maintaining corporate formalities, the Trustee must remain independent from the Grantor to prevent accidental inclusion under IRC §2036 or §2038. The Trustee oversees the asset balance sheet and ensures compliance with the trust instrument provisions.
The Trust Corpus (IDGT Core) serves as the holding reservoir for transferred equity, such as non-voting shares in a family limited partnership (FLP) or real estate holding entity. This sub-system grows shielded from the Grantor’s gross estate.
The Promissory Note acts as the primary transfer mechanism between the Grantor and the Trust Core. It establishes an installment sale contract backed by an Applicable Federal Rate (AFR) interest standard, preventing the transfer from being flagged as an uncompensated gift under IRC §2512.


The Beneficiaries represent the terminal nodes of the system layout. They receive discretionary or mandatory income distributions free of estate, gift, and generation-skipping transfer (GST) taxes upon trust maturity.
| System Component | Governing IRC Section | Technical Parameter / Specification |
|---|---|---|
| Grantor Trust Defect Trigger | IRC §675(4)(C) | Power to substitute assets of equivalent value in a non-fiduciary capacity. |
| Seed Capital Ratio | Treas. Reg. §25.2511-1 | Minimum 10% equity ratio relative to the total installment sale note value. |
| Promissory Note Interest Rate | IRC §1274(d) / §7872 | Minimum Applicable Federal Rate (AFR) based on note duration (Short, Mid, Long). |
| Estate Tax Exclusion | IRC §2033 / §2036 | Complete decoupling from Grantor’s gross estate upon execution of non-retained interest sale. |
Under Revenue Ruling 85-13, the IRS does not recognize sales or transactions between a grantor and their grantor trust as taxable events for income tax purposes. Consequently, no capital gains tax is realized when assets are sold to the IDGT in exchange for a promissory note.
How to Read the Intentionally Defective Grantor Trust Schematic


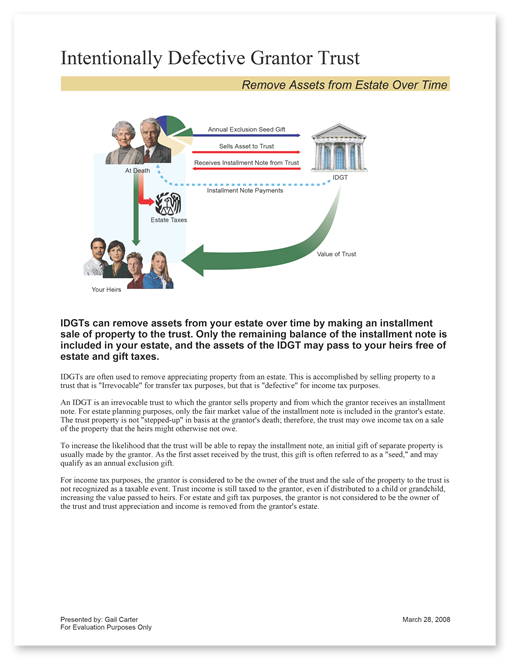
Reading an intentionally defective grantor trust diagram requires tracking three distinct vector paths: capital funding paths, asset sale paths, and debt-servicing feedback loops. Following these vectors sequentially ensures full mechanical understanding of the system dynamics.
Vector 1: Seed Capital Injection
The initial sequence begins with the Grantor making an irrevocable gift of seed capital into the IDGT container. According to standardized financial engineering guidelines, this funding vector must equal at least 10% of the total target asset value intended for subsequent purchase. The gift utilizes a portion of the Grantor’s lifetime gift tax exemption under IRC §2505 and is reported on IRS Form 709. This seed capital creates economic substance, ensuring the trust has independent capacity to service debt.


Vector 2: Asset Transfer via Installment Sale


In the second phase, the Grantor transfers appreciation-yielding equity (such as business entity interests or real estate holdings) to the IDGT Core in exchange for an arm’s-length promissory note. As shown in the diagram above, the note principal equals the appraised fair market value of the transferred equity, often discounted for lack of marketability and minority interest when using a family limited partnership (FLP) asset layout. Because the entity is income-tax-defective, this transfer is recognized as a non-event by the IRS, bypassing capital gains realization.
Vector 3: Debt Servicing and Income Flow
The asset corpus generates cash flow (dividends, rental income, distribution payouts). The Trustee utilizes this cash stream to service the interest and principal payments on the promissory note back to the Grantor. The interest rate is pegged to the minimum published Applicable Federal Rate (AFR) under IRC §1274(d). Any yield generated by the asset corpus above the designated AFR rate remains inside the trust balance sheet, accruing directly for the beneficiaries without incurring gift tax.
Vector 4: Tax Obligation Bypass Loop


Because the trust incorporates an intentional defect (such as IRC §675(4)(C) power of asset substitution), all taxable income generated by the corpus flows directly onto the Grantor’s personal Form 1040. The Grantor pays income tax on the trust’s earnings using external personal funds. This payment is legally classified as a mandatory statutory obligation, not a constructive gift to the trust, allowing the trust corpus to compound completely undiluted by federal or state income taxes.
Promissory notes within an IDGT architecture can be structured as interest-only payments with a balloon payment at maturity (typically 9 to 15 years). The interest rate is locked at the current mid-term or long-term AFR rate on the date of contract execution.
Engineered System Configuration of an IDGT Architecture


Proper configuration of an intentionally defective grantor trust diagram requires precise balancing of regulatory leverage points, valuation rules, and structural safeguards. A failure in system configuration can cause the structure to default to standard trust classification, triggering immediate gift tax or estate tax inclusion.
When engineering the trust blueprint, select one or more specific IRC grantor defect triggers. Integrating redundant defect switches can prevent accidental cure of grantor status during the trust operational cycle.
- IRC §675(4)(C) Substitution Power: Grants the Grantor (or a designated non-fiduciary) the power to reacquire trust assets by substituting other property of equivalent value. This switch triggers grantor trust status for income tax without pulling assets back into the estate under IRC §2036.
- IRC §677(a) Distribution Power: Allows trust income to be distributed to or accumulated for the benefit of the Grantor’s spouse, locking in grantor trust rules under IRC §672(e).
- IRC §674(a) Power to Control Beneficial Enjoyment: Authorizes a non-adverse trustee to alter beneficial enjoyment among a class of beneficiaries without requiring consent from adverse parties.
To maximize system efficiency, contrast this setup against a grantor retained annuity trust (GRAT) structural schematic. While GRATs require annuity payouts based on statutory IRC §7520 hurdle rates and risk mortality failure if the Grantor dies during the term, an IDGT locks in lower AFR interest rates and allows perpetual wealth transfer when paired with a dynasty trust perpetuities blueprint.


Do not allow the Grantor to serve as Trustee while holding discretionary power over income distributions. Doing so creates a fatal retainment of control under IRC §2036 and §2038, collapsing the estate tax shield and pulling the entire asset corpus into the Grantor’s gross estate upon death.
Troubleshooting Failures in an Intentionally Defective Grantor Trust Layout
System failure in an IDGT blueprint generally presents as an IRS audit recharacterization, valuation challenge, or loss of grantor status. Below are common structural failure modes, operational symptoms, and diagnostic protocols used to correct the layout.
1. Structural Collapse: Recharacterization under IRC §2036
Symptom: The IRS asserts that the installment sale was not a bona fide sale for adequate consideration, classifying the transaction as a transfer with a retained life interest under IRC §2036(a)(1).
Diagnostic Cause: The trust lacked sufficient seed capital prior to the sale, or note payments were strictly dependent on trust asset performance with zero independent capitalization. The promissory note resembled equity rather than valid debt.
Correction Protocol: Ensure the trust maintains a strictly documented 10% minimum equity seed capital baseline prior to executing the note. Perform formal loan servicing: issue demand notices, execute timely interest wire transfers, and maintain corporate balance sheets reflecting real debt obligations.
2. Note Recharacterization: Imputed Gift under IRC §7872


Symptom: Tax authority asserts an uncompensated gift tax liability on the transaction between Grantor and Trust.
Diagnostic Cause: The interest rate specified on the promissory note was lower than the mandatory Applicable Federal Rate (AFR) established by the Treasury for the month of sale, or the note terms were amended mid-stream without adequate consideration.
Correction Protocol: Audit the note terms on execution date against published IRS Applicable Federal Rates. Use exact monthly published rates based on note maturity: Short-Term (3 years or less), Mid-Term (3 to 9 years), or Long-Term (over 9 years). Lock rates via written contract prior to asset transfer.
3. Defect Exhaustion: Inadvertent Termination of Grantor Status
Symptom: The trust files Form 1041 as a complex non-grantor trust, paying compressed trust-level income tax rates (reaching the top tax bracket at low income thresholds) and issuing Schedule K-1s to beneficiaries.
Diagnostic Cause: The chosen defect mechanism (e.g., power of substitution or power to add beneficiaries) was relinquished, or a trustee change eliminated the non-adverse party holding the power.
Correction Protocol: Audit the governing trust document for backup defect provisions. Re-establish non-fiduciary power holders by appointing an independent distribution advisor authorized under the trust instrument to hold IRC §675(4)(C) powers.
| Failure Mode | IRS Risk Exposure | Diagnostic Indicator | Remedial Action |
|---|---|---|---|
| Inadequate Seed Capital | IRC §2036 Estate Inclusion | Seed capital ratio less than 10% of debt value | Inject additional equity capital via gift tax exemption allocation. |
| Below-Market Interest | IRC §7872 Deemed Gift | Note interest rate < official published AFR | Re-issue promissory note at exact applicable published AFR rate. |
| Grantor Serves as Fiduciary | IRC §2038 Revocable Transfer | Grantor holds distribution discretion over corpus | Execute immediate resignation of Grantor; appoint independent trustee. |
Intentionally Defective Grantor Trust Diagram Technical FAQ
Why is the system architecture named “intentionally defective”?
The structure is designated as “intentionally defective” because trust draftspersons deliberately include specific provisions (defects) under IRC §§671–679 that force the trust to fail grantor trust income tax neutrality. While historically viewed as drafting mistakes, these defects are deliberately engineered so that the Grantor remains liable for income taxes while the underlying principal remains successfully removed from the Grantor’s gross estate under transfer tax law (IRC Chapter 11).
What is the minimum seed capital percentage required in an IDGT blueprint?
While the Internal Revenue Code does not state a explicit statutory minimum percentage, administrative practice and prevailing case law (such as Fidelity-Philadelphia Trust Co. v. Smith) establish a standard minimum threshold of 10% equity relative to the total value of the installment note purchase price. This 10% buffer provides the trust with independent economic substance, proving to auditors that the transaction is a legitimate loan sale rather than a retained equity transfer.
How does Revenue Ruling 85-13 affect transactions within the trust schematic?
Revenue Ruling 85-13 is the foundation of the IDGT installment sale strategy. It establishes that a grantor and their grantor trust are treated as the same taxpayer for federal income tax purposes. Consequently, any transaction between the Grantor and the IDGT—including selling appreciated assets in exchange for a promissory note or receiving interest payments—is considered a non-taxable self-transaction. No capital gains are realized on the sale, and interest paid on the note is not taxable income to the Grantor.
What happens to the IDGT system layout if the Grantor dies before the note is fully paid?
If the Grantor dies prior to the complete payoff of the promissory note, the principal value of the unpaid note remains inside the Grantor’s gross estate for estate tax accounting under IRC §2033. However, all post-sale appreciation on the assets transferred to the IDGT stays inside the trust, completely shielded from estate tax. The tax treatment of unamortized note gain at death is complex; tax positions vary between treating the note as receiving a step-up in basis under IRC §1014 or recognizing gain on installment obligations under IRC §691.
Which tax forms are required to report operations within the IDGT layout?
The initial seed capital gift is reported by the Grantor on IRS Form 709 (United States Gift and Generation-Skipping Transfer Tax Return). Annually, the Trustee files an informational IRS Form 1041 (U.S. Income Tax Return for Estates and Trusts). Instead of paying tax or issuing K-1s, Form 1041 includes a “Grantor Trust Statement” attachment detailing all income, gains, deductions, and credits, which the Grantor incorporates directly onto their personal Form 1040 (Schedule E / Schedule D).
Step-by-Step Guide to Understanding the Intentionally Defective Grantor Trust Diagram
Identify – Define the grantor, trustee, and beneficiary roles within the trust configuration.
Locate – Position the initial 10% seed capital gift in the trust layout to ensure debt absorption capacity.
Reference – Use current IRS Applicable Federal Rates (AFR) to structure the promissory note interest terms.
Connect/Route – Transfer appreciating assets to the IDGT structure in exchange for installment promissory note payments.
Verify – Confirm that grantor trust rules (IRC 671-679) apply for income tax while excluding assets from estate tax.
Troubleshoot – Adjust trust income allocation or note repayment schedules if cash flow constraints arise.